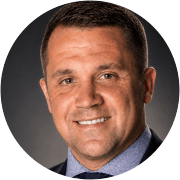
Craig Oliver is a later life lending adviser based in Garforth, in east Leeds. If you own your home in North Yorkshire and you are over 55, this page covers what homes here are worth and the property questions that come up in a county of seaside towns, market towns and moorland villages.
Advice can be over the phone, by video call, or face to face, whichever suits you.
Where this page covers
North Yorkshire is a big county, and it is now a single council area. This page is for homeowners across it, including:
- The coast: Scarborough, from the South Bay round to the North Bay below the castle headland, Whitby beneath the abbey on the East Cliff, Robin Hood's Bay and Filey
- The cathedral city and the Nidd: Ripon, with its cathedral at the heart of the city, and Knaresborough, with the railway viaduct over the River Nidd
- The Dales side: Skipton, below Skipton Castle, and the villages out into the Yorkshire Dales
- The Moors and the Vale: the market towns and villages on the edge of the North York Moors
- Selby and the south of the county: Selby, around the abbey, and the villages towards Leeds
Harrogate and York have pages of their own: equity release in Harrogate and equity release in York.
What homes here are worth
These are the average prices from HM Land Registry's UK House Price Index for April 2026, the latest month in our data, rounded down to the nearest thousand. Because North Yorkshire is a single council area, the Land Registry publishes one figure for the North Yorkshire Council area. Our figures do not include separate numbers for Scarborough, Whitby or Selby. The county figure includes Harrogate but not York, which is counted separately.
| North Yorkshire | Average price |
|---|---|
| All homes | around £270,000 |
| Terraced | around £219,000 |
| Semi-detached | around £271,000 |
| Detached | around £433,000 |
| Flat | around £142,000 |
For comparison, the average across the Yorkshire and The Humber region was around £207,000.
Every one of those averages, flats included, sits well above the £70,000 minimum property value for a lifetime mortgage. But a county average covers a seafront flat in Scarborough and a Dales farmhouse alike. These are indicative area averages, not a valuation of any individual property. When you apply, the lender arranges an independent valuation of your home, and that is the figure that counts.
You can check how prices have moved on our house price tracker.
Contains HM Land Registry data © Crown copyright and database right 2025. This data is licensed under the Open Government Licence v3.0.
On the coast: Scarborough, Whitby and Filey
It has to be the home you live in. A lifetime mortgage is taken out on your main home. If you also own a holiday let or second home, or your home has substantial land or an annexe, those are things to check with the lender early.
Flats and apartments, including the converted seafront buildings, are eligible, but lease length matters. A lease generally needs more than 75 years left on it, and it is worth checking early rather than late.
Older fishermen's cottages and terraces in the old towns are ordinary residential property and generally fine, though some older homes have features that need checking with a lender rather than assumed.
In the Dales and on the Moors
Homes with land, or with an annexe, need checking with the lender early. Large acreage and annexes are not ruled out, but they go to a lender for a decision rather than through a standard assessment, so raise them early.
Stone cottages and village houses are ordinary residential property and generally straightforward.
Non-standard construction is not an automatic no. It is referred to a lender for a decision rather than declined out of hand, and lenders take different views, which is where being whole of market earns its keep.
Ripon, Knaresborough and Selby
The market towns sit somewhere between the two. Terraced and semi-detached homes are ordinary residential property for a lender. Ex-local authority housing is not a bar in itself, though individual lenders have their own criteria.
What to weigh up
Equity release will reduce the value of your estate, and the money released could affect your entitlement to means-tested benefits. On a lifetime mortgage where the interest is not paid, interest is charged on the interest as well as the original loan, so the amount owed can grow significantly over time. Early repayment charges can apply for a number of years. Our advice is always to borrow only what you need. For a first idea of the figures, see how much equity can I release.
Sometimes there is a better route: a retirement interest only mortgage, downsizing, a benefit going unclaimed, or doing nothing at all. Craig will tell you when equity release is not the answer.
What we can look at
- Lifetime mortgages, whole of market
- Retirement interest only (RIO) and term interest only (TIO) mortgages, independent whole of market advice
- Interest only mortgages for ages 50 and over, independent whole of market advice
- Home reversion, referred to sector specialists
Questions we get asked in North Yorkshire
Can I use equity release on my holiday cottage or second home?
No. A lifetime mortgage is always taken out on your main residence, the home you live in.
My house has land or an annexe. Is that a problem?
Not necessarily. Large acreage and annexes go to a lender for a decision rather than through a standard assessment, so mention them when you first call.
Is my seafront flat suitable?
Flats are eligible, but the lease generally needs more than 75 years remaining. Check yours early.
Is my house worth enough?
Your home needs to be worth at least £70,000. In April 2026 the Land Registry average for every property type in North Yorkshire was well above that, though only a valuation of your own home tells you where you stand.
Can you come and see me in Scarborough or Skipton?
Advice can be over the phone, by video call, or face to face, whichever suits you. Craig is based in Garforth, in east Leeds, and visits clients across North Yorkshire.
What does the advice cost?
The first conversation is free. Our advice fee is a maximum of £1,495, payable only if your case completes. Other lender and solicitor fees may apply.
Not sure how any of this applies to your own circumstances? Craig is happy to talk it through, free and with no obligation.
Talking to us
You pay no advice fee unless your case completes. Other lender and solicitor fees may apply.
Book a call with Craig or call 0113 403 5584.